
Roof Insurance Essentials: Coverage, Claims, and Tips for Homeowners
Essential Roof Insurance: What Homeowners Need to Know
Roof insurance coverage typically falls into two categories: Actual Cash Value (ACV) and Replacement Cost Value (RCV). Your policy’s limits and premiums depend on factors like your roof’s age, condition, and material. Common causes of damage include severe weather, such as strong winds and heavy rainfall, as well as wildlife intrusion and natural ageing.
When filing a claim, promptly notify your insurer, document the damage thoroughly with photographs and professional assessments, and choose qualified contractors for repairs. Regular maintenance and inspections can prevent costly issues and ensure continued coverage.
Understanding your policy details, including potential coverage limitations for older roofs, is vital for protecting your home. It’s crucial to be aware of local building regulations, which may affect your insurance coverage and repair options.
Popular roofing materials in our region include slate, clay tiles, and synthetic alternatives that mimic traditional styles while offering improved durability. Given our often unpredictable weather patterns, it’s wise to consider additional protection against wind-driven rain and potential flooding. Some insurers offer enhanced policies that cover these specific risks.
To maintain your roof’s integrity and insurance validity, schedule annual inspections, particularly after stormy seasons. Keep gutters clear of debris and trim overhanging branches to minimise the risk of damage during high winds.
When selecting a policy, inquire about coverage for listed buildings or properties in conservation areas, as these may require specialised insurance. Additionally, check if your policy includes protection against unexpected issues like dry rot or woodworm, which can affect timber roof structures.
By staying informed and proactive, you can safeguard both your roof and finances, ensuring peace of mind regardless of what the weather may bring.
Key Takeaways
Essential Roof Insurance Guidelines for Homeowners
Understanding Roof Cover Types:
Familiarise yourself with different insurance options, particularly the distinction between Actual Cash Value (ACV) and Replacement Cost Value (RCV) policies. These choices significantly impact your potential payout in the event of damage.
Routine Maintenance is Key:
Schedule regular roof inspections and upkeep to prevent deterioration and maintain your insurance cover. Many policies require evidence of proper maintenance for claims to be valid.
Common Causes of Roof Damage:
Be aware of typical threats to your roof’s integrity, including severe weather events like gales and heavy rainfall, natural ageing processes, and wildlife such as nesting birds or rodents.
Policy Limits and Roof Condition:
Regularly review your policy limits to ensure they align with your roof’s current age and condition. Older roofs or those with pre-existing issues may require additional cover.
Documenting Damage for Claims:
In the event of roof damage, thoroughly document the affected areas with clear photographs and detailed notes. Contact your insurer promptly to initiate the claims process, adhering to any time limits specified in your policy.
Local Considerations:
Ensure your policy accounts for region-specific factors such as slate tiles in heritage areas or additional waterproofing for properties in flood-prone zones. Familiarise yourself with local building regulations that may affect repair or replacement work.
Weather-Resistant Materials:
Consider investing in weather-resistant roofing materials suited to our climate, such as robust clay tiles or high-quality synthetic slate. These may offer better long-term protection and potentially lower insurance premiums.
Energy Efficiency Upgrades:
Explore options for incorporating energy-efficient roofing solutions, like solar tiles or enhanced insulation. Some insurers offer incentives for eco-friendly improvements that can also reduce your energy bills.
Types of Roof Insurance Coverage
Types of Roof Insurance Cover
When it comes to roof insurance cover, homeowners typically encounter two main types: Actual Cash Value (ACV) and Replacement Cost Value (RCV). These cover options differ remarkably in their approach to compensating homeowners for roof damage. With increasing concerns about climate resilience, some insurers now offer additional cover for weather-resistant materials and sustainable roofing options.
ACV policies factor in depreciation when calculating payouts. This means that as your roof ages, the amount you’ll receive for a claim decreases. Whilst ACV policies often come with lower premiums, they may leave you with substantial out-of-pocket expenses if your roof needs replacement.
On the other hand, RCV policies cover the full cost of replacing your roof without considering depreciation. Although these policies generally have higher premiums, they provide more extensive protection, especially for older roofs.
The age, condition, and material of your roof play vital roles in determining your cover eligibility and premium differences. Roofs over 20 years old may face limited cover options or higher premiums due to increased risk. Conversely, high-quality materials like slate or clay tiles can lead to lower premiums, as they offer better protection against severe weather events.
It’s important to carefully consider these factors when choosing your roof insurance cover to guarantee adequate protection for your home. Local building regulations may also impact your cover, particularly if you live in a conservation area or have a listed property.
Popular roofing materials in our region include slate, clay tiles, and concrete tiles, each offering unique benefits in terms of durability and aesthetics. When selecting a roofing material, it’s crucial to consider our often unpredictable weather patterns, including heavy rainfall, strong winds, and occasional snowfall.
Some insurers now offer incentives for installing eco-friendly roofing options, such as green roofs or solar tiles. These sustainable choices not only contribute to energy efficiency but may also qualify for reduced premiums or extended cover.
Remember to review your policy regularly, especially after any major roofing work or improvements. Keeping your insurer informed about the condition and maintenance of your roof can help ensure you have the most appropriate cover for your property.
Common Causes of Roof Damage
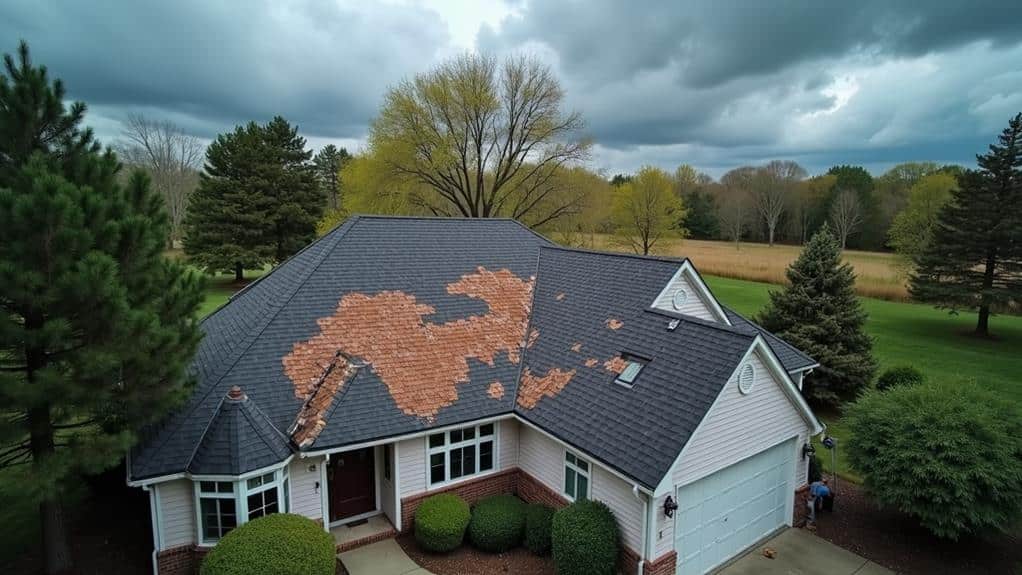
Top Culprits Behind Roof Damage
Your home’s first line of defence against the elements faces myriad threats that can lead to significant deterioration. Weather-related destruction, including fierce storms, hailstones, and gale-force winds, often tops the list of common causes, whilst ageing and wear issues gradually compromise your roof’s integrity over time.
In our damp climate, moss and algae growth pose particular challenges, potentially leading to moisture retention and subsequent rot. Homeowners should also be vigilant about potential damage from wildlife, such as nesting birds or squirrels, which can create vulnerabilities in the roofing structure.
When it comes to materials, slate and clay tiles are popular choices due to their durability and aesthetic appeal. However, these can be susceptible to cracking or slipping, especially in areas prone to freeze-thaw cycles.
For flat roofs, which are common in many urban areas, waterproofing membranes like EPDM or GRP require regular inspection to prevent leaks.
It’s crucial to adhere to local building regulations, which may dictate specific requirements for roof pitch, materials, and insulation standards. Regular maintenance, ideally carried out by a professional roofer registered with the National Federation of Roofing Contractors (NFRC), can help identify and address issues before they escalate into costly repairs.
Weather-Related Roof Destruction
Weather-Related Roof Destruction
The unpredictable nature of our climate poses a significant threat to the integrity of your roof. Severe weather events can cause extensive damage, compromising your home’s protection. Whilst hailstorms are less common, they can still occur, with hailstones potentially damaging tiles and weakening your roof’s structure. Wind damage is a major concern, with gusts exceeding 50 mph capable of loosening or removing tiles, exposing your roof to further harm.
Heavy rainfall presents its own challenges, particularly when accompanied by gale-force winds. These conditions can exploit existing vulnerabilities in older roofs, causing water damage and leaks. In colder months, snow accumulation and subsequent thawing can lead to ice dams, resulting in structural issues and water ingress.
| Weather Event | Potential Damage | Impact Severity |
|---|---|---|
| Gale-force winds | Missing tiles | Moderate to High |
| Heavy rainfall | Water damage | Moderate |
| Snow/Ice dams | Leaks, structure | Moderate |
| Severe storms | Multiple issues | High |
The frequency of weather-related roof damage is significant, with approximately 30% of homeowners filing insurance claims for such issues. This statistic underscores the importance of regular roof inspections and maintenance to mitigate potential damage and ensure your insurance coverage adequately protects your home against these common weather-related risks.
When considering roof repairs or replacements, it’s crucial to select materials that comply with local building regulations and are suitable for our climate. Popular choices include slate, clay tiles, and concrete tiles, all of which offer excellent durability and weather resistance. For flat roofs, EPDM rubber and GRP fibreglass are becoming increasingly favoured options due to their longevity and waterproofing properties.
It’s worth noting that certain areas may have specific requirements for conservation zones or listed buildings. Always consult with a qualified roofer who is well-versed in local planning regulations before undertaking any major roofing work.
Regular maintenance is key to extending the life of your roof and preventing costly repairs. This includes clearing gutters, checking for loose or damaged tiles, and ensuring proper ventilation in your loft space. By taking these proactive steps and working with a reputable roofing company, you can protect your home from the worst of our varied and often challenging weather conditions.
Aging and Wear Issues
Longevity inevitably leads to deterioration, and roofs are no exception. As your roof approaches the 20-year mark, it’s vital to be aware of the ageing and wear issues that can compromise its integrity. Cracked or missing tiles, often resulting from prolonged UV exposure and extreme weather, are common signs of an ageing roof. These issues increase your home’s vulnerability to leaks and structural damage.
Concrete tiles, known for their durability, can extend your roof’s lifespan by 5-10 years compared to standard clay tiles, potentially delaying the onset of age-related problems.
Another concern is the growth of moss and algae, which can trap moisture and accelerate roof deterioration. This is particularly problematic in our damp climate. To extend your roof’s lifespan and maintain its effectiveness, implement regular maintenance strategies. Conduct thorough inspections to identify wear-related issues early, preventing costly repairs and potential insurance claim denials due to neglect.
It’s important to note that many insurance policies limit coverage for roofs older than 20 years, emphasising the need for timely replacements. By staying proactive with your roof maintenance, you’ll not only protect your home but also guarantee continued insurance coverage. Remember, addressing ageing and wear issues promptly can save you significant expenses in the long run and maintain your roof’s protective function.
When considering a roof replacement, it’s crucial to adhere to local building regulations and obtain necessary planning permissions, particularly if you live in a conservation area or listed building.
Popular roofing materials in our region include slate, which offers excellent durability and a classic aesthetic, and fibre cement slates, which provide a similar look at a lower cost.
Given our unpredictable weather patterns, from heavy rainfall to occasional high winds, it’s essential to choose roofing materials and designs that can withstand these conditions. Proper ventilation and insulation are also key considerations, helping to prevent issues like condensation and heat loss, which are common concerns in our climate.
Wildlife and Pest Damage
Whilst homeowners often focus on weather-related roof damage, wildlife and pests can wreak havoc on your roof’s integrity. Grey squirrels, foxes, and various bird species may gnaw through roofing materials, creating entry points for moisture and leading to leaks and structural issues.
Wood-boring beetles can compromise wooden roof structures, resulting in costly repairs if not addressed promptly. Nesting activities by birds and rodents can block drainage systems, potentially causing water accumulation and roof collapse during heavy downpours.
Regular roof surveys are vital for identifying these issues early, as they can help prevent extensive damage and maintain the overall integrity of your roofing system.
To protect your roof from wildlife and pest damage, consider implementing these wildlife prevention strategies and pest control measures:
- Conduct regular surveys to identify signs of intrusion, such as droppings, nests, or gnawed materials
- Install preventive measures like bird spikes and sealed vents to deter wildlife access
- Consult with pest control professionals to develop a thorough protection plan
It’s important to address wildlife and pest issues promptly to prevent extensive damage. Your buildings insurance policy may cover some types of wildlife and pest damage, but prevention is key to avoiding costly repairs and potential claim denials.
By implementing these strategies and maintaining vigilance, you’ll better protect your roof from the destructive effects of wildlife and pests.
When selecting roofing materials, consider options that are resistant to local wildlife, such as slate or clay tiles. These materials not only provide excellent protection against the elements but also deter pests from causing damage.
For timber frame structures, ensure that all wooden components are properly treated to resist wood-boring insects.
Remember to comply with local planning regulations when making any significant changes to your roof. Some areas may have restrictions on certain materials or alterations, particularly in conservation areas or listed buildings.
Always consult with a qualified roofing professional who’s well-versed in local building regulations and can advise on the best solutions for your property.
Regular maintenance is crucial in our damp climate. Moss and lichen growth can be particularly problematic, creating ideal conditions for pests and retaining moisture that can damage roofing materials.
Schedule bi-annual roof cleanings, ideally in autumn after leaf fall and in spring to prepare for summer showers.
By taking a proactive approach to roof maintenance and pest control, you can ensure your property remains protected against both wildlife intrusions and our unpredictable weather patterns.
A well-maintained roof not only safeguards your home but also adds value to your property in the long run.
Understanding Your Policy Limits
Understanding Your Policy Limits
As you delve into the intricacies of roof insurance, grasping your policy limits becomes crucial. Home insurance policies typically set maximum payout limits for various claim types, which can vary markedly depending on your insurer and chosen coverage. It’s essential to regularly review and adjust these limits to ensure they align with your property’s current value and contents. Failure to do so can result in coverage gaps and out-of-pocket expenses during a claim.
Your policy limits can be influenced by factors such as your roof’s age and condition. Older roofs often face lower coverage caps due to increased risk. Be aware that certain claims may have sub-limits for specific items or damage types, restricting the amount you can recover for those losses.
Understanding the implications of policy limits is important, as exceeding them during a claim can lead to partial reimbursement or claim denial. To avoid these pitfalls, regularly assess your coverage and make necessary policy adjustments. This proactive approach will help ensure you’re adequately protected and minimise potential financial setbacks in the event of roof damage or other property-related incidents.
When considering your roofing needs, it’s worth noting that local building regulations may impact your coverage. For instance, listed buildings or properties in conservation areas may require specific materials or techniques, which could affect your policy limits.
Popular roofing materials such as slate, clay tiles, and synthetic slate alternatives each come with their own considerations for insurance purposes.
Regional weather patterns also play a significant role in determining appropriate coverage. Areas prone to high winds or heavy rainfall may require additional protection against storm damage. Conversely, properties in drier regions might benefit from coverage that addresses the risk of sun damage to roofing materials.
By staying informed about these factors and working with a reputable roofing contractor, you can make informed decisions about your property’s protection. Regular roof inspections and maintenance can help mitigate risks and potentially lower your insurance premiums.
Remember to communicate any significant changes or improvements to your insurer to ensure your policy remains up-to-date and comprehensive.
The Roof Insurance Claim Process

A Guide to Navigating Roof Insurance Claims
When you discover damage to your roof, the first step is to promptly ring your insurance company to initiate the claims process. It’s crucial to schedule a professional inspection from a qualified roofer to thoroughly document the damage and obtain repair estimates.
Given our unpredictable weather, from heavy rainfall to occasional storms, it’s not uncommon for roofs to suffer wear and tear. Whether you have traditional slate tiles, popular concrete tiles, or modern flat roofing systems, proper documentation is key to a successful claim.
Gather all necessary paperwork, including detailed photographs and estimates from licensed contractors. Be sure to consider any relevant building regulations that may affect repairs or replacements, particularly if you reside in a conservation area or own a listed property.
When selecting materials for potential repairs, keep in mind regional factors. Clay tiles are a common choice in southern regions, while slate is often preferred in northern areas due to its durability in harsher conditions.
Submit your comprehensive documentation to your insurer, ensuring you’ve included all pertinent information about your roof’s current state and the proposed remedial work. This thorough approach will facilitate a smoother review process by your insurance company.
Filing the Initial Claim
Filing the Initial Claim
When faced with roof damage, lodging an initial insurance claim is a crucial step towards repair or replacement. The claim timeline commences with promptly contacting your insurer to report the damage and set the claims process in motion. This swift action is vital for documenting the incident and ensuring timely processing of your claim.
Obtaining a detailed condition report can provide valuable insights into your roof’s overall state and help identify any pre-existing issues that may affect your claim.
Following the initial report, you’ll need to schedule a professional roof survey. This inspection serves two primary purposes:
- Documenting the extent of the damage
- Obtaining repair estimates
- Providing expert assessment for your claim submission
As you progress through the initial steps, it’s imperative to thoroughly document all damage yourself. Take clear, detailed photographs and make extensive notes about the roof’s condition. This evidence will substantiate your claim and provide valuable support during the review process.
Once you’ve gathered all necessary documentation, including the survey report, photographs, and repair estimates, submit these materials to your insurer. This thorough submission allows for efficient processing of your claim.
Upon approval, you can then proceed with scheduling the required repairs or replacement, adhering to the coverage outlined in your policy.
It’s worth noting that certain roofing materials, such as slate or clay tiles, are particularly popular due to their durability and aesthetic appeal in our climate.
Additionally, given the frequent occurrence of wind and rain, ensuring proper installation and regular maintenance is crucial for longevity.
When selecting a roofing contractor, verify that they comply with all local building regulations and possess the necessary qualifications, such as membership in the National Federation of Roofing Contractors (NFRC). This ensures that your roof repair or replacement adheres to the highest standards of quality and safety.
Inspection and Documentation Process
The inspection and documentation process often forms the backbone of a successful roof insurance claim. After filing your initial claim, it’s vital to schedule a professional roof survey. This step is of utmost importance, as the surveyor will provide detailed documentation of the damage and repair estimates required by your insurance company.
During this process, you’ll need to thoroughly document all visible damage yourself. Take clear, high-quality photographs from multiple angles and make detailed notes about the extent of the damage. These documentation tips will support your claim and help guarantee a smoother approval process.
Once the survey is complete, you’ll receive an extensive report outlining the damage and estimated repair costs. It’s essential to submit this report, along with all other required documentation, to your insurance company promptly. This includes your own photographs and notes, as well as any additional estimates you’ve obtained from roofing contractors.
When selecting materials for repairs or replacements, consider options that can withstand our damp climate, such as slate or clay tiles. These materials aren’t only aesthetically pleasing but also offer excellent durability against frequent rainfall and occasional high winds.
It’s crucial to ensure that any roofing work complies with local building regulations, particularly in conservation areas or for listed buildings. Your chosen roofing contractor should be well-versed in these regulations and able to advise on appropriate solutions that meet both legal requirements and your personal preferences.
Remember that regular maintenance is key to prolonging the life of your roof, especially given our changeable weather patterns. Schedule annual inspections to check for loose tiles, damaged flashing, or blocked gutters, which can all lead to more significant issues if left unaddressed.
Documenting Roof Damage Effectively

Proper documentation of roof damage is vital for a successful insurance claim. When photographing damage, ensure you capture clear, high-resolution images of all visible issues, including close-ups of broken tiles, leaks, and structural problems. These photographs serve as significant evidence for your claim.
Don’t forget to document the date and time of the damage occurrence, along with any contributing weather conditions, such as storms or heavy rainfall. Given the lengthy waiting times for roofers, which average 9 weeks, it’s crucial to document damage promptly to avoid further deterioration.
Create a thorough list of all damaged areas and items, detailing descriptions, estimated repair costs, and necessary materials. This list will support your claim’s value and provide a clear overview of the extent of the damage. Additionally, retain any professional inspection reports or estimates from roofing contractors, as these documents add credibility to your claim.
To facilitate a smooth claims process, follow these important steps:
- Keep a detailed record of all communication with your insurance company
- Document dates, times, and names of representatives you speak with
- Maintain a chronological file of all claim-related documents and correspondence
When selecting materials for repairs or replacements, consider popular options such as slate, clay tiles, or concrete tiles, which are well-suited to our climate and adhere to local building regulations.
It’s essential to choose a reputable roofing contractor who’s familiar with regional weather patterns and can recommend appropriate solutions for your property. Remember that certain areas may have specific planning permissions or conservation requirements, particularly for listed buildings or properties in conservation areas.
Always consult with your local council before undertaking any major roofing work to ensure compliance with regulations.
Lastly, regular maintenance is key to preventing extensive damage. Schedule annual inspections, especially after harsh winter weather, to identify and address any issues before they escalate. This proactive approach can save you time, money, and the hassle of dealing with complex insurance claims in the long run.
Choosing a Qualified Roofing Contractor
Choosing a Qualified Roofing Contractor
Selecting a qualified roofing contractor is a crucial step in ensuring your roof repair or replacement is completed to the highest standards. To make an informed decision, prioritise contractors with a proven track record, verified licences, and appropriate insurance coverage. This protects you from potential liabilities and guarantees the work meets industry standards.
Look for contractors who offer comprehensive roofing services for domestic, commercial, and industrial properties, as they’re likely to have extensive experience in various roofing types.
Before finalising your choice, research online reviews and testimonials from previous clients. These insights will help you gauge the contractor’s reliability and quality of workmanship. Obtain at least three quotes from different contractors to compare pricing, scope of work, and materials used. This comparison allows you to choose the best value for your specific roofing needs.
When evaluating contractor qualifications, request a detailed written estimate that includes all costs, project timelines, and warranties. This extensive document helps you avoid unexpected charges during the project.
Consider hiring local roofing professionals, as they’re familiar with regional weather challenges and building regulations that can affect the installation process. Their local expertise can contribute to a more efficient and compliant roofing project, ensuring your investment is protected for years to come.
It’s essential to check that your chosen contractor is well-versed in popular roofing materials such as slate, clay tiles, and felt. They should also be knowledgeable about the latest energy-efficient options and sustainable roofing solutions. Given the often wet and windy climate, your roofer should be experienced in installing proper drainage systems and waterproofing measures to prevent leaks and water damage.
Ensure your contractor is registered with a reputable trade association, such as the National Federation of Roofing Contractors (NFRC). This membership demonstrates their commitment to quality and adherence to industry standards.
Additionally, verify that they comply with current health and safety regulations, including working at height guidelines set by the Health and Safety Executive (HSE).
Navigating Insurance Claim Denials
Navigating Insurance Claim Denials for Roof Repairs
Steering through insurance claim denials can be a challenging and frustrating process for homeowners dealing with roof damage. To improve your chances of a successful claim, it’s vital to understand common claim denial reasons and implement effective insurance appeal strategies. Make sure you’re familiar with your policy’s exclusions and limitations, as claims for damages not covered by your insurance will likely be denied automatically.
Timely reporting is essential, as insurers often have specific deadlines for filing claims. Missing these timelines can result in denial, particularly crucial when dealing with storm damage or sudden leaks. If your claim is denied, remember that you have the right to appeal by providing additional evidence or clarification to support your case.
To navigate insurance claim denials effectively for roofing issues:
- Compile thorough documentation, including photographs of damaged tiles or slates, and repair estimates from qualified roofers.
- Understand and address common denial reasons, such as lack of maintenance or pre-existing conditions like moss growth or cracked flashing.
- Be prepared to file an appeal with additional evidence if necessary, such as a detailed inspection report from a certified roofing surveyor.
When dealing with insurers, it’s crucial to be aware of local building regulations and how they impact roofing repairs or replacements. For instance, listed buildings or properties in conservation areas may have specific requirements that affect the materials and methods used in repairs.
Consider the impact of regional weather patterns on your roof. Coastal areas may require more frequent maintenance due to salt air exposure, while properties in areas prone to high winds might need additional reinforcement. Insurers will take these factors into account when assessing claims.
Popular roofing materials like slate, clay tiles, and synthetic alternatives each have their own maintenance requirements and lifespans. Ensure you’re following manufacturer guidelines for care and upkeep to avoid claim denials based on neglect.
Preventative Maintenance for Roof Longevity

Proactive measures can often prevent the need for insurance claims altogether when it comes to your property’s roof. Regular maintenance is key to extending your roof’s lifespan and avoiding costly repairs. Implement seasonal checklists to ensure you’re conducting bi-annual inspections, ideally in spring and autumn. These inspections can identify potential issues early, saving you from more substantial problems down the line.
Considering the increasing importance of climate resilience in building design, it’s vital to choose roofing materials that can withstand our often unpredictable weather conditions and contribute to energy efficiency.
During these checks, focus on cleaning gutters and downpipes to prevent water backup, which can lead to leaks and structural damage. Promptly replace any damaged or missing tiles to maintain your roof’s integrity. Proper loft ventilation is essential for reducing heat and moisture buildup, which can cause mould growth and tile deterioration.
Consider applying a protective coating or sealant to guard against UV damage and weather-related wear. This can greatly enhance your roof’s lifespan and effectiveness. Be sure to review your roof guarantees and adhere to their maintenance requirements to keep them valid.
Popular roofing materials in our region include slate, clay tiles, and concrete tiles, each offering unique benefits and aesthetics.
When selecting a roofing contractor, ensure they’re registered with the National Federation of Roofing Contractors (NFRC) and comply with current building regulations. These regulations cover aspects such as thermal insulation, fire safety, and structural integrity.
Our maritime climate, characterised by frequent rain and occasional high winds, necessitates robust roofing solutions. Consider installing additional weatherproofing features such as dry verges and hip systems to protect against wind-driven rain and potential storm damage.
By implementing these preventative measures, you’re not only protecting your home but also potentially reducing the likelihood of insurance claims and maintaining lower premiums over time.
Impact of Claims on Premiums

Impact of Claims on Insurance Premiums
When lodging a claim for roof repairs or replacement, homeowners should be aware of potential increases in their insurance premiums upon policy renewal. Insurers reassess risk profiles based on claim history, which may affect one’s no-claims bonus and future discounts.
It’s crucial to weigh the immediate benefit of claim payouts against long-term cost implications, particularly for minor damages that mightn’t exceed the excess.
In the roofing industry, considerations extend beyond mere financial aspects. Local building regulations play a significant role in determining the scope and nature of repairs or replacements. For instance, listed buildings or properties in conservation areas may require specialised materials and techniques to maintain historical authenticity.
Popular roofing materials vary across regions, with slate being a common choice in many areas due to its durability and aesthetic appeal. Clay tiles are another favoured option, particularly in southern regions where Mediterranean-inspired architecture is prevalent.
In more modern developments, concrete tiles offer a cost-effective alternative without compromising on quality.
Weather considerations are paramount when assessing roof damage and planning repairs. The typically wet climate necessitates robust waterproofing measures, while occasional severe storms call for enhanced wind resistance.
Coastal areas face additional challenges from salt air corrosion, requiring specialised treatments and materials.
Homeowners should also be mindful of energy efficiency regulations. Proper insulation and ventilation not only improve comfort but can also lead to reduced energy bills and potential tax benefits.
Many roofing companies now offer eco-friendly options, such as solar tiles or green roofing systems, which align with growing environmental concerns and regulations.
Premium Increases After Claims
Roof Insurance Claims: Navigating Premium Increases
Filing a roof insurance claim can significantly impact your future premiums. Insurers view claims as indicators of potential future risks, leading to premium increases ranging from 20% to 40%, depending on the claim’s severity and frequency. This premium assessment process considers your overall claims history, with multiple claims in a short period potentially resulting in steeper hikes or even policy non-renewal.
While a single claim typically doesn’t trigger penalties, each subsequent claim increases your perceived risk, affecting future premium costs. It’s essential to understand your policy terms, as some insurers offer features like vanishing excesses or loyalty discounts that can help offset premium increases after claims.
To navigate the complexities of roof insurance claims and their impact on premiums, consider the following:
- Assess the necessity of filing a claim, weighing potential premium increases against out-of-pocket repair costs.
- Review your policy’s claim frequency limits and understand how multiple claims might affect your coverage.
- Explore options for mitigating premium increases, such as raising your excess or implementing preventative maintenance measures.
When dealing with roof insurance claims, it’s crucial to consider the unique aspects of our climate and building regulations. For instance, the prevalence of slate and clay tiles in many areas requires specialised knowledge for proper installation and repair.
Moreover, our propensity for damp weather means that addressing issues promptly is paramount to prevent further damage.
Local building regulations, such as those pertaining to listed buildings or conservation areas, may impact the materials and methods used in roof repairs or replacements. It’s advisable to consult with a professional roofer who’s well-versed in these regulations to ensure compliance and maintain the integrity of your property.
Popular roofing materials like Welsh slate, concrete tiles, and synthetic slate alternatives each have their own insurance considerations. Understanding how your choice of roofing material affects your policy and potential claims is essential for making informed decisions.
To mitigate the risk of claims and subsequent premium increases, consider implementing a regular maintenance schedule. This might include annual inspections, clearing gutters, and addressing minor issues before they escalate into major problems.
Many reputable roofing companies offer maintenance packages tailored to local weather conditions and common roofing types.
By taking a proactive approach to roof maintenance and understanding the intricacies of your insurance policy, you can better navigate the claims process and minimise the impact on your premiums.
Long-Term Insurance Cost Considerations
Long-Term Insurance Cost Considerations for Your Roof
When it comes to maintaining your home’s roof, it’s crucial to consider the long-term impact on your buildings insurance premiums. The frequency of claims plays a significant role in how insurers assess your risk profile. Filing multiple claims within a policy year can lead to increased premiums, as insurers may view this pattern as indicative of higher risk.
Each claim you make could result in the loss of no-claims discounts, greatly affecting your overall insurance costs at renewal time.
Being aware of your excess is essential when considering whether to file a claim. Claims below your excess amount won’t be covered, leaving you responsible for out-of-pocket expenses without affecting your premium. However, even claims above the excess can influence future pricing.
Insurers may reassess your coverage terms and pricing after a claim, potentially leading to changes in policy limits or exclusions. Understanding how claims impact your premiums is vital, as some policies have specific clauses dictating how previous claims affect future pricing and eligibility for discounts.
When considering roof repairs or replacements, it’s important to factor in local building regulations and popular materials. For instance, slate and clay tiles are common choices due to their durability and suitability for our climate.
Additionally, with the increasing frequency of severe weather events, investing in storm-resistant roofing materials could potentially reduce the likelihood of future claims.
Given the unpredictable nature of our weather, from heavy rainfall to occasional high winds, regular roof maintenance is crucial. This proactive approach not only helps prevent costly damage but may also positively influence your insurance risk assessment.
By carefully considering the long-term financial implications of filing a claim and investing in quality roofing solutions, you can make informed decisions that balance immediate needs with future insurance costs.
Upgrading Roof Materials After Claims
After a Roof-Related Insurance Claim: Upgrading Your Materials
Following a successful insurance claim for roof damage, homeowners have a prime opportunity to enhance their roofing materials. Opting for superior-quality options like slate or zinc can bolster your property’s resilience and potentially reduce your insurance premiums. These materials offer improved resistance to our notoriously unpredictable weather, making them a sound investment for the future.
Consider eco-friendly roofing tiles that incorporate recycled materials, contributing to environmental sustainability while providing excellent protection. Such green options often come with enhanced warranties and impact ratings, which are particularly beneficial given our frequent storms and occasional hail.
When replacing your roof post-claim, remember to:
- Meticulously document all upgrades
- Liaise with your insurer about new materials
- Ensure the upgrades meet coverage requirements
Upgrading your roof materials can restore full insurance eligibility, especially if your previous roof exceeded two decades in age. Some insurance policies incentivise the use of impact-resistant materials, which may qualify you for discounts on premiums after a claim.
These roof material benefits extend beyond insurance savings, as they also increase your property value and minimise long-term maintenance costs.
Popular roofing materials in our region include:
- Natural slate: Ideal for traditional and listed buildings
- Clay tiles: Suitable for various architectural styles
- Synthetic slate: A lightweight alternative to natural stone
- Standing seam metal: Growing in popularity for modern homes
When selecting new materials, consider local planning regulations, especially if you reside in a conservation area or own a listed property. Additionally, factor in our maritime climate, which can affect certain materials differently than in other parts of the world.
It’s crucial to weigh the initial investment against potential savings and benefits over time. By making informed decisions about your roofing materials after a claim, you’re not only protecting your home but also optimising your insurance coverage and financial outlook.
Consult with a qualified roofing professional to determine the best options for your specific circumstances and local area requirements.
Frequently Asked Questions
How Do I Claim a New Roof on My Homeowners Insurance?
Claiming a New Roof Through Your Home Insurance: A Guide for Property Owners
When your roof has suffered significant damage, you may be able to claim a replacement through your home insurance. To initiate this process, it’s crucial to contact your insurer straightaway. Arrange for a professional roofer to conduct a thorough inspection of your property’s roof. This expert assessment will provide valuable documentation for your claim.
Gather comprehensive evidence to support your case. This should include detailed reports of the damage, precise estimates for repairs or replacement, and high-quality photographs showcasing the extent of the issue. Weather events such as severe storms or high winds are often covered by standard policies, so be sure to note any recent extreme weather in your area.
Popular roofing materials in our region include slate, clay tiles, and concrete tiles, all of which offer excellent durability against our oft-inclement weather. However, each material type may be subject to different coverage terms, so review your policy carefully.
Be mindful of local building regulations when considering a roof replacement. Many councils require planning permission for significant alterations, particularly in conservation areas or for listed buildings. Your chosen roofing company should be well-versed in these requirements and can guide you through the process.
Remember that insurers typically cover sudden and unexpected damage rather than general wear and tear. Regular maintenance is key to ensuring your roof remains in good condition and compliant with your policy terms. Consider scheduling annual inspections to catch potential issues early and maintain your roof’s integrity against our challenging climate.
How Do I Make a Successful Home Insurance Claim?
Making a Successful Home Insurance Claim for Roof Damage
When your roof has been damaged, filing an insurance claim can feel daunting. However, by following these steps, you can navigate the process with confidence and improve your chances of a favourable outcome.
Firstly, contact your insurer straight away. Many policies have strict time limits for reporting incidents, so don’t delay. Take thorough photographs and videos of the damage, paying particular attention to any missing tiles, cracked slate, or compromised flashing.
Understand your policy inside and out. Be aware of your excess and any exclusions, particularly those related to gradual deterioration or lack of maintenance. Many insurers won’t cover damage caused by general wear and tear, so it’s crucial to keep up with regular roof inspections and repairs.
Document all communication with your insurer and keep receipts for any emergency repairs or temporary measures taken to prevent further damage. If you’ve had to relocate due to extensive damage, retain records of these expenses as well.
Consider seeking professional assistance from a qualified roofer. They can provide an expert assessment of the damage and give you a detailed report to support your claim. Look for tradespeople registered with the National Federation of Roofing Contractors (NFRC) to ensure quality workmanship.
Be mindful of regional weather patterns when discussing your claim. For instance, if you live in an area prone to high winds or heavy rainfall, these factors may have contributed to the damage and should be noted.
Lastly, familiarise yourself with local building regulations. Any repairs or replacements must comply with current standards, which may differ from when your property was originally built. This knowledge will help you understand the scope of work required and ensure your claim adequately covers all necessary repairs.
Can I Claim for a Leaking Roof on Insurance?
A leaky roof can be a nightmare for any homeowner, but knowing whether you can claim on your insurance is crucial. Generally, you may be able to claim for a leaking roof if it’s caused by a peril covered in your policy. However, it’s important to note that regular roof maintenance is not just recommended, it’s essential.
When considering a claim, insurers will look at the cause of the leak. Storm damage, for instance, is often covered, whereas gradual deterioration due to lack of upkeep typically isn’t. Given our unpredictable weather patterns, with frequent rain and occasional severe storms, it’s vital to keep your roof in top condition.
If you suspect a leak, it’s wise to document the damage thoroughly. Take photographs and keep records of any repairs or maintenance you’ve carried out. Engaging a professional roofer for an inspection can provide valuable evidence for your claim. Many reputable roofing companies offer comprehensive reports that can support your case.
When selecting roofing materials, consider options that stand up well to our climate. Slate and clay tiles are popular choices, offering both durability and aesthetic appeal. For flat roofs, EPDM rubber or fibreglass systems are increasingly favoured for their waterproof properties.
It’s crucial to report any damage to your insurer promptly. Delays could potentially affect the success of your claim. Be prepared to provide details of when you first noticed the leak and any steps you’ve taken to mitigate further damage.
Remember, building regulations play a significant role in roofing work. Ensure any repairs or replacements comply with current standards, including energy efficiency requirements. This not only keeps you on the right side of the law but can also improve your home’s insulation and reduce heating costs.
Can You Claim for a Flat Roof on House Insurance?
Whilst pitched roofs are more commonplace, flat roofs present their own set of unique challenges for homeowners. When it comes to claiming for a flat roof on your home insurance, it’s crucial to thoroughly review your policy. Coverage can vary significantly depending on the materials used and the specific terms outlined by your insurer.
In our damp and often unpredictable climate, flat roofs require special attention to ensure they remain watertight and durable. Popular materials for flat roofs include EPDM rubber, GRP fibreglass, and modified bitumen. Each of these options offers distinct advantages, with EPDM being particularly favoured for its longevity and resistance to our frequently wet weather.
Local building regulations play a significant role in flat roof construction and maintenance. It’s essential to ensure that any work carried out meets current standards, particularly regarding insulation and drainage. Many councils now require flat roofs to have a slight pitch to prevent water pooling, which can lead to leaks and structural damage.
When considering insurance for your flat roof, be aware that some policies may have exclusions or limitations. Insurers often view flat roofs as higher risk due to their susceptibility to water damage. It’s wise to inform your insurer about your flat roof and discuss any specific requirements they may have, such as regular inspections or maintenance schedules.
For those living in coastal areas or regions prone to high winds, additional considerations may apply. Storm damage is a common concern, and ensuring your flat roof is properly secured and regularly maintained can help mitigate risks and improve your chances of a successful claim should the need arise.
Conclusion
Protecting Your Home’s Crown: A Guide to Roof Insurance and Maintenance
As a homeowner, you’ve now acquired crucial insights into roof insurance, types of cover, and the claims procedure. While navigating insurance matters can seem daunting, remember that proper documentation and regular upkeep are paramount. Don’t allow worries about increased premiums to discourage you from lodging legitimate claims. Instead, concentrate on safeguarding your investment.
Consider crafting a visual timeline of your roof’s lifespan, including inspections, repairs, and claims, to better monitor its history and anticipate future requirements. This approach is particularly useful given our unpredictable climate, with its frequent rain, occasional snow, and gusty winds.
When selecting roofing materials, bear in mind local building regulations and popular choices such as slate, clay tiles, and concrete tiles. These options not only comply with conservation area guidelines but also withstand our diverse weather conditions admirably.
Regular inspections by qualified roofers are essential, especially after severe weather events. They can identify potential issues early on, preventing more significant damage and costlier repairs down the line. Keep detailed records of these inspections, as they may prove invaluable when dealing with insurers.
Speaking of insurers, familiarise yourself with the nuances of buildings insurance policies. Some may offer additional cover for things like chimney damage or moss removal, which are common concerns in our damp climate.
Lastly, consider energy efficiency when maintaining or replacing your roof. Proper insulation and ventilation can significantly reduce heating costs, a growing concern for many households. Some local councils even offer grants for energy-efficient home improvements, including roof upgrades.
By staying informed and proactive, you can ensure your roof remains in top condition, protecting your home and potentially saving on insurance premiums in the long run.


